Morning update | Research cutoff: October 29, 2026, 9:13 a.m. New York time (EDT). This first edition covers the preceding 24 hours. It was prepared after the scheduled 6 a.m. release and is being published when ready. Reporting periods and transaction status are identified below.
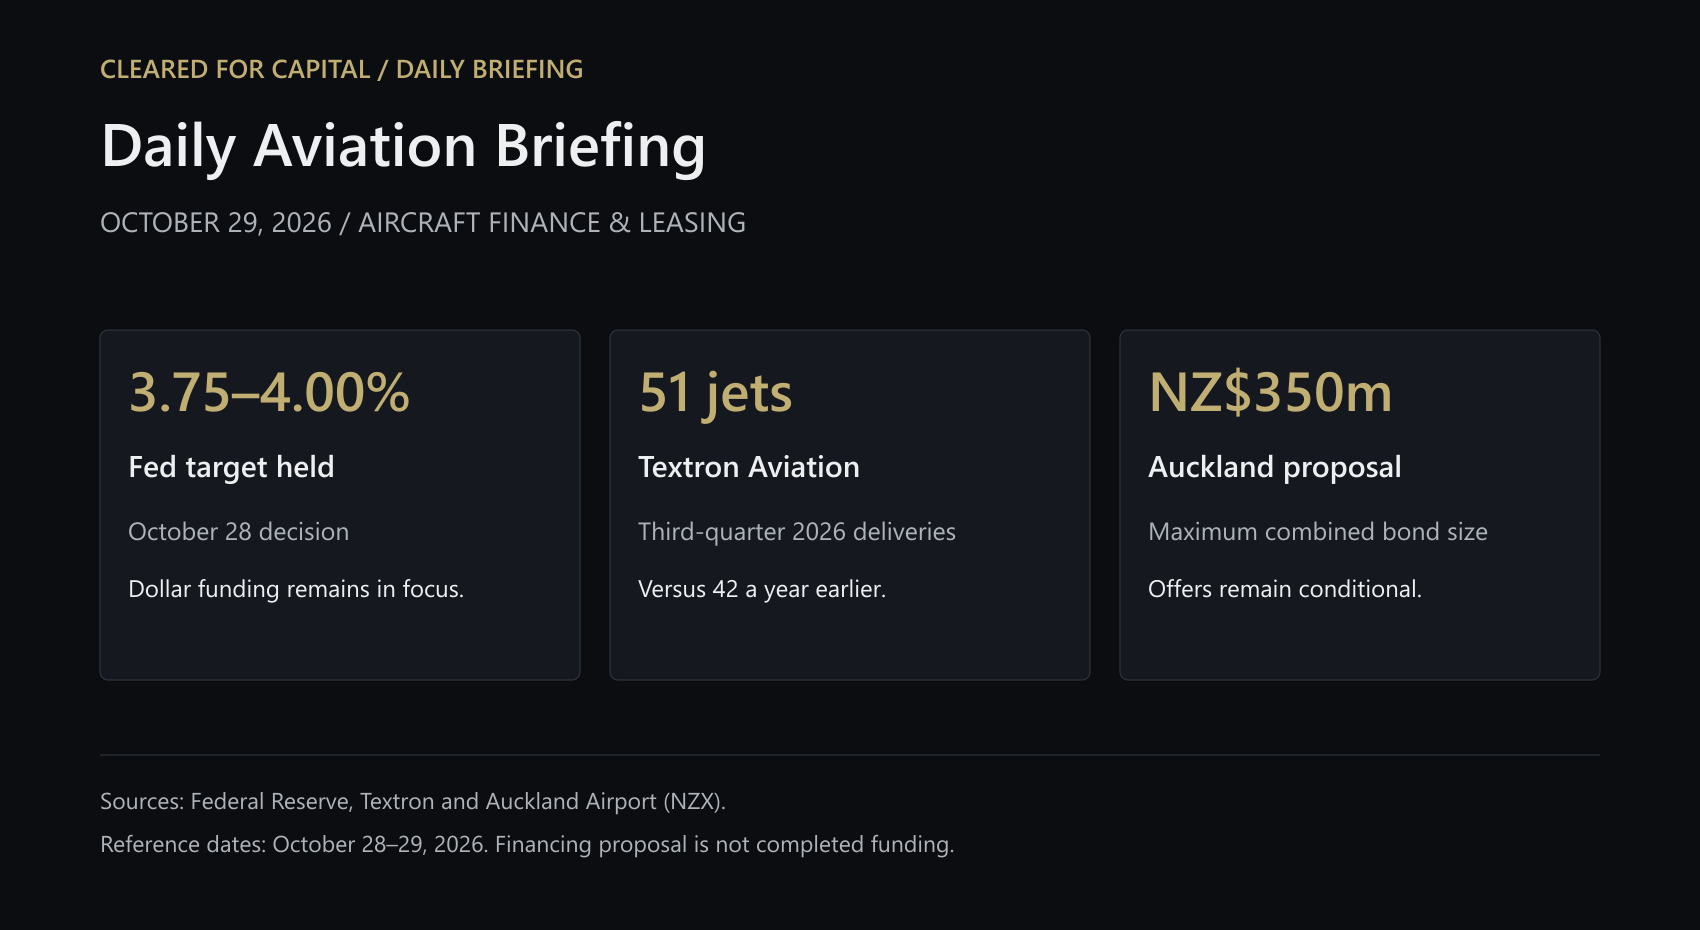
The Federal Reserve held its policy range, the UK set out a conditional engine-development framework, and fresh fleet disclosures showed where capital is being committed and aircraft are being delivered. For owners and lenders, the useful signals are the terms still to be agreed, the aircraft actually in service, and the cash flows supporting the next round of investment.
Aircraft & Engines
UK–Rolls-Royce framework remains conditional. The UK government’s October 28 announcement describes a joint, ten-year £2.5 billion programme for next-generation civil and defence engine technologies, including the single-aisle opportunity. The financing qualification is important: no new grants have yet been awarded, and future support remains subject to approvals, negotiations and legal processes. Government announcement; Budget documentation.
Our assessment: this is a long-term industrial-policy signal. A lender evaluating an aircraft delivery or an engine replacement should distinguish that framework from an awarded development contract, a certified product or a customer order.
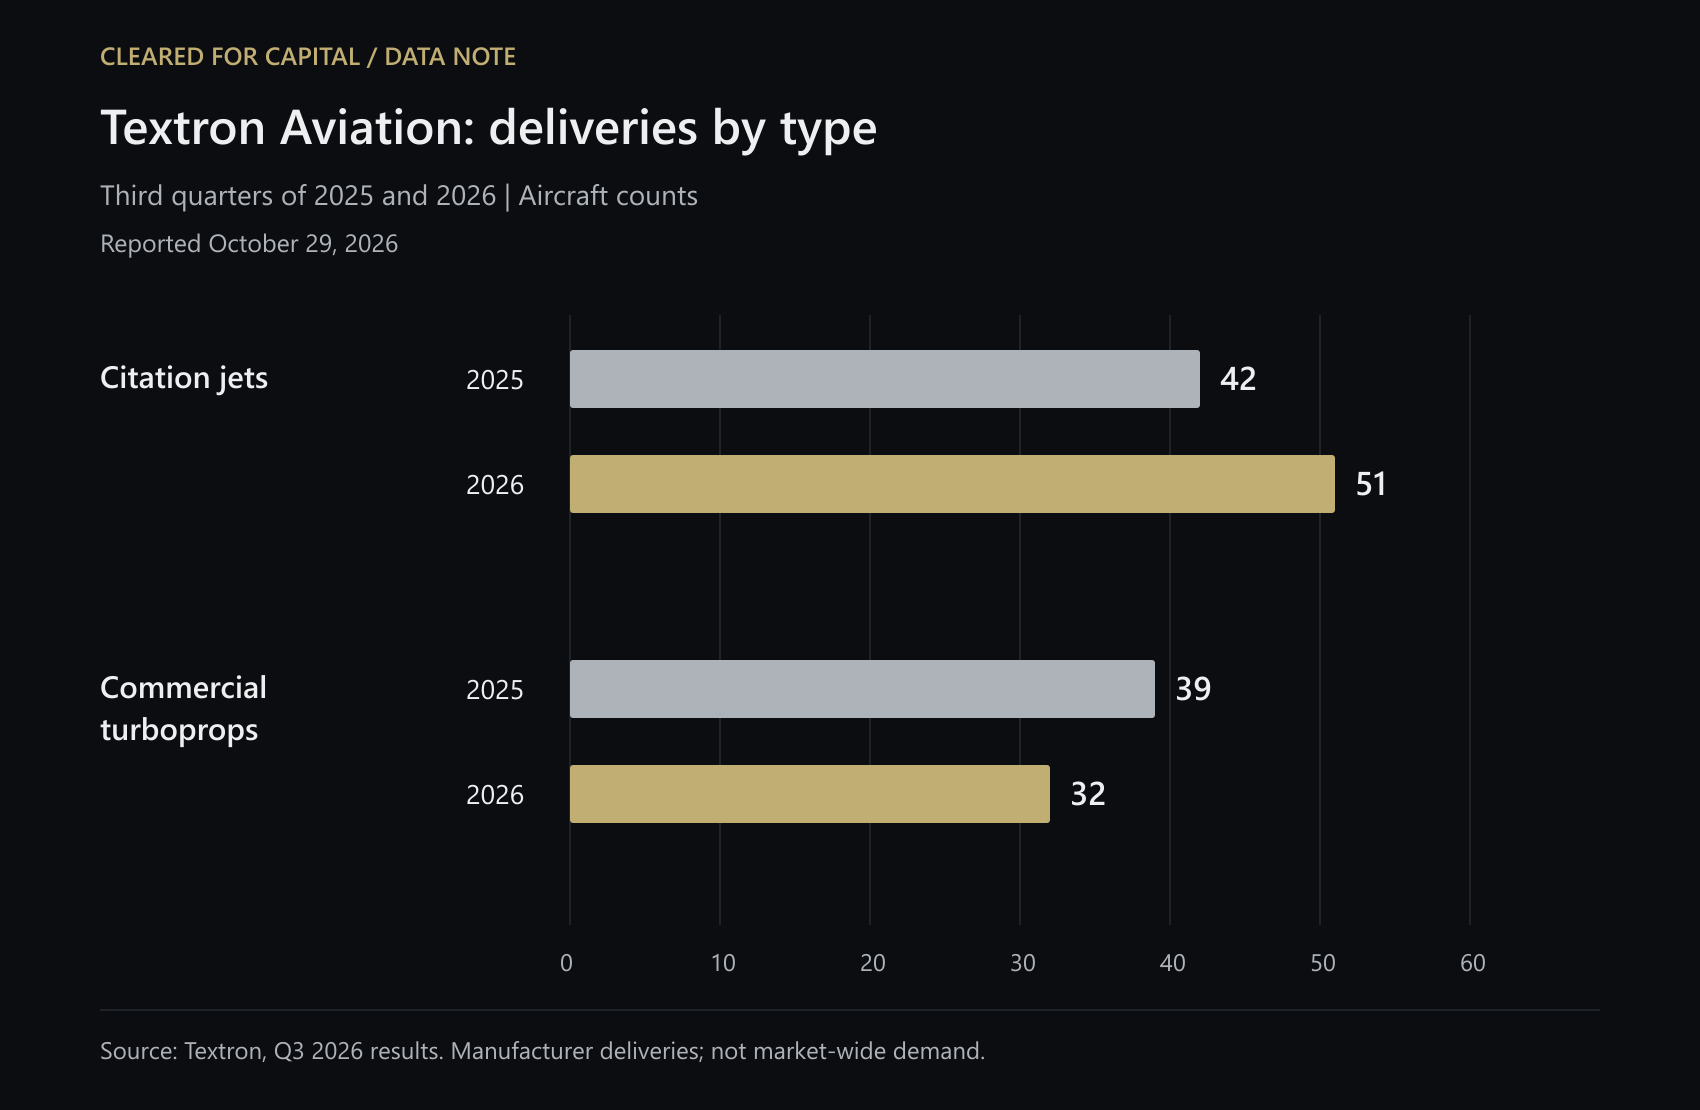
Business-aviation production is uneven. Textron Aviation reported 51 jet deliveries in Q3 2026, compared with 42 a year earlier, while commercial turboprops fell to 32 from 39. Its quarter-end backlog was $8.0 billion. The mix matters when assessing delivery timing and funding requirements for particular aircraft types; these counts do not establish a market-wide demand trend. Textron’s October 29 release.
Airspace / Airports
Auckland Airport is considering bond offers. Its October 29 NZX notice outlines possible five-year fixed-rate bonds maturing in November 2031 and wholesale floating-rate bonds maturing in November 2029. If both proceed, their combined maximum size would be NZ$350 million. Details are expected in the week of November 2, subject to market conditions. No retail money is currently being sought, and applications cannot yet be made. Auckland Airport / NZX.
Why it matters: pricing and execution are still ahead. Airport funding conditions offer context for the wider aviation capital market, but airport bonds have different obligors, assets and credit protections from aircraft-backed debt.
Alliances / Mergers
Canada’s competition concerns keep airline coordination under review. In an October 28 report to the transport minister, the Competition Bureau said a proposed Air Canada–United arrangement would likely harm competition on ten Canada–US routes. The airlines account for all non-stop passenger traffic on five of them, according to the Bureau. The existing 2012 restrictions remain in force; the minister’s public-interest review will determine whether the arrangement is authorized. Competition Bureau release.
Our assessment: fleet and revenue assumptions should reflect the current permissions. The Bureau’s finding is a review milestone, with final authorization still to be determined. This is an airline-coordination proposal rather than a merger closing.
Earnings / Fundings
FTAI reports results and a planned buyback. Its October 29 release reports Q3 net income attributable to shareholders of $149.1 million and consolidated adjusted EBITDA of $348.3 million, a non-GAAP measure. It intends to enter a $500 million accelerated share repurchase with Royal Bank of Canada and expects completion in Q4. The prospective agreement and completion timing should be retained when describing this capital-allocation decision. FTAI results and transaction wording.
Fleet / Transactions
FTAI’s acquisition update is cumulative. The same release says SCI I had closed 212 of 301 committed aircraft through September 30. It expects substantially all remaining commitments to close by year-end. SCI II ended the quarter with 109 aircraft committed. These quarter-end programme figures were disclosed today. The year-end completion expectation remains forward-looking, and committed aircraft still require execution. FTAI’s fleet-program disclosure.
Maintenance / Safety
Austrian Airlines adds Embraer component-pool support. In a release datelined October 29, Embraer says its agreement covers Austrian’s current fleet of 13 E195s and more than 300 components, with exchange, repair and overhaul support. The webpage’s publication label is October 28. Embraer announcement.
Our assessment: pooling can support aircraft availability and reduce the operator’s need to hold every spare itself. Owners and lenders should still examine coverage, exclusions and aircraft-return obligations; the announcement does not quantify realized maintenance savings.
Management / Government
The Fed holds at 3.75–4.00%. The October 28 statement, released at 2 p.m. EDT, maintained the federal-funds target range by a 10–2 vote. Both dissenters preferred a quarter-point increase. The statement describes inflation as elevated. Federal Reserve statement.
Implication for financing: dollar-funded aircraft borrowers received no new policy-rate reduction from this meeting. Actual debt service continues to depend on the loan’s contractual benchmark, credit spread and hedging. A policy hold alone does not establish a new aircraft lease rate or refinancing quote.
Network / Traffic
Air Transat adds five planned Canada–Europe routes. Its October 29, 7 a.m. ET announcement adds Montreal–Geneva and Toronto–Birmingham as new destinations for summer 2027, alongside Quebec City–Lyon, Quebec City–Barcelona and Montreal–Faro. The specified seasonal operating periods begin in June 2027. Montreal–St. Maarten and Quebec City–Puerto Plata will also extend into year-round service. Air Transat’s programme and route table.
Why it matters: this gives lessors and airport counterparties a forward view of planned aircraft deployment. Published schedules remain future capacity plans; they do not establish realized traffic, load factors or profitability.
Forward calendar
October 29: the ECB calendar lists its monetary-policy meeting and press conference today. This edition does not report an ECB decision beyond its research cutoff. October 30, 8:30 a.m. New York time: the US Bureau of Labor Statistics schedules the Q3 Employment Cost Index, a further input to inflation and funding expectations.